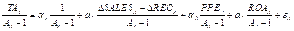Contents
Download PDF
pdf Download XML
1374 Views
537 Downloads
Share this article
Review Article | Volume 3 Issue 2 (July-Dec, 2022) | Pages 1 - 7
Impact of Nomination and Governance Committee Attributes on Earnings Management of Listed Firms on the Nigerian Exchange Group
 ,
 ,
1
Department of Accountancy, Nnamdi Azikiwe University, Awka, Anambra State, Nigeria
Under a Creative Commons license
Open Access
Received
July 4, 2022
Revised
Aug. 22, 2022
Accepted
Sept. 15, 2022
Published
Oct. 10, 2022
Abstract

All-encompassing corporate governance structure in firms especially the existence of diligent and independent nominating/governance committee is key to the overall wellbeing of organisations. This study uses 76 sample firms and a holistic earnings management model to assess the effects of the nomination/governance committee's qualities (diligence and independence) on the management of earnings for listed non-financial enterprises on the Nigerian Exchange Group from 2012 to 2021. Using Stata 13.0 software for both descriptive statistics and simple regression methods, two study hypotheses were created and tested (OLS). The findings showed that measures of nomination/governance committee diligence exert positive significant influence on earnings management of listed firms on Nigerian Exchange Group while nomination/governance committee independence exerts negative significant influence on earnings management of listed firms on Nigerian Exchange Group. Also, the introduced control variables (sales growth and market capitalisation) have a negative relationship and significant effect earnings management of Some Selected Listed Corporations in Nigeria. Subsequently it was recommended upon this study that management of companies should not emphasis too much on the role of nomination/governance committee especially in the areas of diligence (frequency of meetings) but on the independence of nomination/governance committee in relation to earnings management and regulatory bodies should shift emphasis on how financial estimates prepared can be devoid of earnings management.

Keywords
INTRODUCTION

All-encompassing corporate governance structure in firms especially the existence and independence of nominating/governance committees cannot be over emphasized. De Jong et al. [1] resolved that board composition is a key determinant of board effectiveness. The nomination/governance committee's principal responsibility is always to identify and choose board members. Riabichenko [2] posit that the existence of nominating/governance committee improves board independence. Consequently, one can argue that an adequate and well constituted nomination/governance committee can nominate and select the best candidates for the board of directors which will not only reduce agency costs but also help in mitigating earnings management. The view of this study was corroborated by earlier studies such Azar et al. [3] that separating management and control by creating a nominating/governance committee is an important step in ensuring that committee members are independent and free from influence. A board or recruitment committee will be judged compared to other board members based on their choices in the process of recruitment. They have the task of recruiting directors that would be effective monitors of management and are therefore interested in upholding their own reputations and thus recruit people that would do a good job. For instance, Puni cites Fernando [4]. He found that through the mechanisms of well-constituted independent committees shaping board decisions and this begins with a nominating/governance committee with unbiased selection and recruitment of the members.


Notably, most Nigerian works in the domain of corporate governance focused on governance attributes and firm performance amongst others [5,6,7,8,9], with little concern on the efficiency of board committee attributes on concepts like earnings management. Outside Nigeria, prior studies on the extent of nomination committees’ influence did not provide information about how characteristics of a nomination or governance committee affect earnings management [10,11,12,13]. There has been a lack of empirical studies examining the attributes of nomination/governance committee’s influence on earnings management in Nigeria despite the important role played by this board sub-committee and how this board sub-committee (nomination/governance committee) attributes can reduce agency problems and discourage earnings management leading to enhanced Earnings Management reporting. This creates an empirical gap that needs to be filled. More so, most studies [4,14,15,16] conducted on nomination committee are done in the financial service sector for a few period of less than seven (7) year thus creating another gap requiring empirical evidence. Due diligence and independence of the nomination/governance committee are examined in this study's relationship to the management of earnings. The following testable research hypotheses were developed and presented in null form in order to accomplish the study's primary goal:


Ho1: Nomination/governance committee diligence does not significantly influence earnings management of listed non-financial firms on Nigerian Exchange Group

Ho2: Nomination/governance committee independence does not significantly influence earnings management of listed non-financial firms on Nigerian Exchange Group


This study on nomination/governance committee attributes’ influence on earnings management of listed non-financial firms on Nigerian Exchange Group with a sample of 107 firms covered a period of 10 years; between 2012 and 2021. 


Literature Review

In this section, the review of relevant literature encompassing the subject matter was done.it covers conceptual review, theoretical review and review of empirical studies.


Concept of Nomination/Governance Committee (NGC)

The NCCG, explicitly stated that the NGC should be composed of Non-Executive Directors (NEDs) with majority being Independent Non-Executive Director (INEDs). The committee is saddled with the responsibility of structure review; in size, composition and commitment of the Board through careful identification of suitably qualified human resources (in terms of skills, knowledge and experience) to become Board members and make recommendations for nomination and appointment, establishing a formal and transparent process for board appointments, institute an official induction and training programme for directors, assessing the performance of directors (in terms of skills, experience and competence) on a continuous basis and designing a reviewable succession policy plan for the Chairman of the Board, the MD/CEO and all other EDs, NEDs and positions of senior managers to ensure proper leadership style and continuity.


Although, the NGC is responsible for selecting qualified people to be appointed to be on the board, sometimes the appointment is made based on the recommendations of the Chairman and this is capable of influencing appointments to the board [17]. According to Kallamu [16], the time the Chairman spent in that position, his shareholding in the company and whether he is part of the company’s founding family member are strong determining factors for the involvement of the Chairman in directors’ appointment and this will affect the independence and effective monitoring of the board since there is high probability that the Chairman will support the appointment of only those who will promote his interest. This Chairman influence in the selection of directors is highly likely in companies where the Chairman is a member and part of the NGC, in companies with small board and in boards dominated by inside directors [18]. On the importance of NGC to companies, Christensen et al. [19] affirmed that nomination committees enhance monitoring process and increase firm performance.


Nomination/Governance Committee Meeting

The lack of empirical studies into the frequency of nomination/governance committee meeting (diligence) and its impact on earning quality and how NGC diligence reduce agency cost and enhance earning quality is crucial to this study. It is believed that frequent NGC meetings is capable of creating an enabling environment to access performance and have a better scorecard of directors and management and this would not only determine unbiased re-election and appointments but also engender integrity among members.


Nomination/Governance Committee Independence

The presence of Independent Non-Executive Directors (INEDs) will not only perfect selection, nomination and appointment of competent, skillful and knowledgeable directors but also facilitate better utilization and management of company resources. The independence of the nomination/governance committee enhances its ability to monitor and discipline firm’s management This position was earlier proposed by Shen and Jia [20], when they assert that an independent nomination committee consisting entirely of independent directors would be better positioned; for this would assist minority shareholders nominate independent directors as candidates. On the contrary, Osma and Noguier [21] earlier revealed that the presence of NGC encourages earnings manipulation and this is often achieved by constraining independent directors’ optimal performance.


Earnings Management (EM) Concept

EM is a purposeful and systematic means of influencing reported earnings by the management to portray a financial information that contrast reality of the company’s financial status for their personal interest. Many scholars have looked into this concept and common among these definitions is the intention of managerial team for managing earnings. 


Theoretical Review

This study draws upon agency and resource dependency theories in line with Ruigrok et al. [14].


Agency Theory 

Agency theory focused mainly on the separation of ownership and controls in organisations. This theory explains the nexus of the principal to the agent, vice-versa and other inherent critical issues arising from delegation of authority [22,23]. The problem of asymmetry of information where the agent is privileged to information within the organisation than the principal leading to conflicting interest between the agent and his principal coupled with the different risk-bearing attitudes of principal and agent are at the heart of agency theory [24]. The theory recommends that manager should act in the best interest of the shareholders and refrain from engaging in self-dealing contracts while the shareholders establish incentives; this would help align the conflict of interest [22,23]. The NGC is one of the board sub-committees that ensures that qualified executives and board members are nominated and appointed to control and reduce agency problems between the principal, the shareholders and agent who are executive management.


Resource Dependence Theory

Resource dependence theory took a different view that the mechanisms of internal corporate governance structures, especially board of directors serves as a connection between the organisation and its scarce resources as well as the effective monitoring of the managers [25]; such that would allay earnings management. According to Haniffa and Cooke [26], the NGC has the Non-Executive Directors (NEDs) and the Independent Non-Executive Directors (INEDs) that can offer invaluable resources ranging from financial expertise, special skills, experience, independent suggestions and knowledge to the principal. Moreover, their reputation (goodwill) can attract contracts, facilitate useful political information and create easy access to capital for the firm [26,27]. It is sometimes argued that boards and committees, who have high connections in their businesses (both in internal and external environment), contribute critical and valuable insights associated with better access to resources. This study will add to the existing literature by adopting both the agency and the resource dependency theories in explaining the impact of NGC attributes and earnings management of listed non-financial service firms on NGX Group.


Review of Empirical Works

Ruigrok et al. [14] examined the impact of nomination committees' board composition, independence and demographic diversity with 210 sample firms in Swizz Stock Exchange from 2001-2003 using probit regression techniques. They found that firms with nomination/governance committees with higher independent and foreign directors, but relatively low female on board as well as nomination/governance committee existence relates positively to diversity in nationality but not diversity in board education status. It was also documented that nomination committee composition is very essential in independent and foreign, but not of female directors’ nomination.


Md. Borhan and Ahsan [14] investigated the determinants of nomination/governance committee in New Zealand from 2000-2007 with sample of 70 firms using a logistic regression. The result indicated that firm size, extent of directors’ busyness and governance regulation are positively associated with nomination/governance committees’ existence, whereas directors’ independence, controlling shareholders and firm leverage do not.


Agyemang-Mintah [28] studied Nomination Committee (NC) relationship with performance of financial firms in the UK from 2000-2011 with 63 firms using OLS regression; it was shown that NC is significant and positively associated with firm’s Market Value.


Kallamu [16] examined the impacts of attributes of NC on firm performance in Malaysia from 2004-2011 with 37 banks. It was found that directors’ financial expertise positively impacts on accounting returns while membership of executive negatively affects accounting returns on nomination committee.
MATERIALS AND METHODS

This study adopted the Ex-post facto research design and the data for the study are secondary in nature and were sourced from the annual reports of Listed Firms on Nigerian Exchange Group. Annual reports for the years 2012-2021 were downloaded from the website of the sampled companies and Machame Ratios Inc. Data Base. The population of the study comprises all non-financial firms out of which 76 firms were carefully sampled using judgmental sampling techniques.


Dependent Variable

The dependent variable in this study is holistic model of earnings management (EARNMGT).


Independent Variable

The independent variable of this study is a measure of corporate governance (Nomination and Governance Committee Attributes):


  • Nomination/Governance Committee meeting (NOMCDIL) is the frequency of nomination and governance committee meetings per year

  • Nomination/Governance Committee independence (NOMCIND) is the fraction of independent board members on nomination and governance committee

  • Regulating variables include sales growth (SALG) and Market Capitalization (MKCP)


Model Specification

The models for this study were developed by the researcher in line with the specific objectives and hypotheses of this study. Since prior studies believes that the quality of earnings depends largely on the combination of both accrual quality and real activities’ manipulation, this study thus derived a holistic model that combined the ideology of both the accrual based models and those of real earnings management. To achieve this, we obtained the residuals of the Performance Matched Model (PM model) of Kothari et al. and combined same with the residuals obtained from the real earnings management model developed by Roychowdhury. These models were used to derive a holistic model that measures earnings management by capturing both the Total Accruals (TA) and real activity manipulations among firms. Accordingly, from the model of Kothari et al., to detect earnings manipulation using Discretionary Accruals (DACC), total accruals was scaled down by the lag of total assets for firm i in year t and a regression model was developed as follows:


   (1)


Additionally, going by the model designed by Roychowdhury, Real Earnings Management (REM) can be derived using the following:


REM = (ACFO* -1) + APROD + (ADISEXP* -1)                  (2)


By combining the above models shown in Eqn. 1 and 2, we derived a holistic model that measures Earnings Management (EARNMGT) as follows:


EARNMGT = DACC + REM                                                     (3)


Thus, EARNMGT = DACC + (ACFO* -1)

 + APROD + (ADISEXP* -1)                                                    (4)


where:

EARNMGT  =  Earnings Management 

DACC            =  Discretionary accruals based on the model of Kothari et al.

REM             =  Real earnings management based on the model of Roychowdhury


Sequel to the above, the following model is developed to test the hypothesis:


EARNMGTit = ƒ (NOMCAttr, SALG, MKCP)                         (5)


EARNMGTit          =              β0 + β1NOMCAttrit + β2SALGit + 

β3MKCPit + εt                                                                                                                    (6)


EARNMGTit               =              β0 + β1NOMCIndit + β2NOMCDilit +

 β3SALGit + β4MKCPit + εt                                                        (7)


where: 

EARNMGT            =  Earnings Management (Measured as indicated above)

NOMCAttr             =  Nomination Committee Attributes

β1… β9                     =  Regressors

it                              =  Firms at time t.

ε                              =  Error Term (variables not captured in the model)


Techniques of Data Analysis

Just like prior ex-post facto studies conducted in Nigeria [29,30,31,32,33], the data collated for use in this study were analyzed using the Ordinary Least Square (OLS) regression technique by means of STATA 13.0. The Pearson Correlation Coefficient Analysis; Inferential Statistics (R2, R2 adjusted and f-test); followed by the test of hypotheses were conducted.


RESULTS AND DISCUSSION

The outcomes of the Statistical Analysis are presented in Table 1.


Table 1 presents the statistical analysis for the variable set of the study. From the results reported, there are 740 observations which is below the 760 observations expected from a sample of 76 firms for a period of 10 years. Noteworthy is 20 observations excluded from the pooled data due to incomplete dataset. Furthermore, the dependent variable of the study, Earnings Management (EARNMGT) recorded a mean and standard deviation of approximately -0.0136 and 0.4817 respectively. This implies that the individual EARNMGT of the sampled firms revolved around the average value with slight deviations of about 0.48% during the study period. The minimum and maximum values reported during the period under review for EARNMGT were -4.5001 and 2.6473 respectively. The implication of having a low standard deviation of about 0.4817 is an indication that on the average, earnings management of the sampled companies are relatively exhibiting similar trends with very slight variations.


With respect to measures of the nomination committee, we noticed that the mean scores recorded for nomination committee independence (NOMCIND) and nomination committee diligence (NOMCDIL) were 0.2077 and 0.4973 respectively. Their respective standard deviations stood at 0.3958 and 1.1731 respectively. These results are indicative of the fact that on the average, at least 20% of the members of the nomination committees of most of the sampled companies are independent directors.


In the case of the control variables, the Sales Growth (SALG) had a mean and standard deviation of approximately 12.2764 and 81.0404 respectively, while Market Capitalization (MKCP) recorded a mean of 6.7777 with a corresponding standard deviation of 0.9670. The large standard deviation for SALG is an indication that the growth in sales of some firms are exponentially at variance with the level of growth in sales recorded by some other firms in the same or similar industry during the study period. 


Correlation Analysis for Measures of NOMCAttr and Earnings Management

This section concerns itself with the presentation of the result of the correlation analysis for the variables used in measuring the relationship between Earnings Management and measures of nomination committee attributes. The result of the correlation analysis was however used to examine the direction of relationship among the measures of variables of interest [34]; and in our case, nomination committee attributes and Earnings Management.
 

Table 1: Descriptive Analysis of the Study’s Variables

VariablesObs.MeanStd.Dev.Min.Val.Max.Val.
EARNMGT740-0.01360.4817-4.50012.6473
NOMCIND7400.20770.395803
NOMCDIL7400.49731.173108
SALG74012.276481.0404-1001354.255
MKCP7406.77770.9674.70429.6205

Source: Field


Table 2: Table Showing Correlation Outcome for Variables

 EARNMGTNOMCINDNOMCDILSALGMKCP
EARNMGT1.0000    
NOMCIND-0.07891.0000   
NOMCDIL-0.01430.77521.0000  
SALG-0.1209-0.0162-0.01741.0000 
MKCP-0.09480.15860.12380.02211.0000

Source: Field


Table 3: Outcomes for Model V – NOMCAttr and Earnings Management

Hypothesis 1 and 2  No. of Obs.: 740
Dependent VariableExplanatory VariablesCoeffStd. Err.ZP > | z |Wald Chi2(5)Prob > Chi2
EARNMGT
 NOMCIND-0.19950650.0403936-4.940.000


34.84


0.0000

 NOMCDIL0.05535040.01211044.570.000
 SALG-0.00017720.0002420-0.730.464
 MKCP-0.02887820.0107261-2.690.007
 _CONS0.20067370.07217612.760.005

Source: Field


Additionally, the outcome regarding the correlation coefficient between pairs of independent variables were used to detect the presence or otherwise of multicollinearity among the measures of the independent variable. – Nomination committee attributes. In this study, nomination committee attributes were measured by nomination committee independence (NOMCIND) and Nomination Committee Diligence (NOMCDIL) while Sales Growth (SALG) and Market Capitalization (MKCP) were also used as control variables. The results of the correlation analysis for EARNMGT, NOMCIND, NOMCDIL, SALG and MKCP are presented in Table 2. 


As noted earlier, Table 2 presents the results for the correlation analysis for the variables used in assessing the relationship between measures of nomination committee attributes and Earnings Management. As shown in the results in Table 2, the coefficients between EARNMGT and the entire explanatory variables (NOMCIND, NOMCDIL, SALG and MKCP) are respectively negative (-0789, -0.0143, -0.1209 and -0.0948). This means that these variables (NOMCIND, NOMCDIL, SALG and MKCP) have negative relationship with EARNMGT. Impliedly, a unit increase in the level of nomination committee independence and diligence will respectively result in an inverse trend in earnings management by listed non-financial companies in Nigeria. Notice also that the correlation coefficient between pairs of the measures of the independent variable (NOMCIND and NOMCDIL), is positive; and has a value of 0.7752 which is below the maximum threshold of 0.8 noted by prior empirical documentations [35].


Furthermore, we observed that for the control variables, SALG and MKCP which recorded negative correlation coefficient with EARNMGT, have low correlation coefficients with the measures of nomination committee attributes. Notice also that while MKCP was found to have positive correlation coefficient with NOMCIND and NOMCDIL, SALG recorded negative coefficients of -0.0162 and -0.0174 with NOMCIND and NOMCDIL respectively. Recall that while positive correlation coefficients signify a positive linkage between pairs of variables, the negative correlation coefficients are indications of negative relationship between such pairs of variables. 


Notwithstanding the above, it is pertinent to note that from the results in Table 2 we also saw that the highest correlation coefficients between pairs of independent variables stood at 0.7752. This was found between NOMCIND and NOMCDIL. With this result, we can argue that the specified model that measures the relationship between Earnings Management and measures of nomination committee attributes using the levels of independence and diligence as proxy for nomination committee attributes is fit and did not show signs of multicollinearity having obtained values less than the threshold of 0.8. In a bid to confirm the above assertion, the variables were further subjected to multicollinearity and other diagnostic tests and the results are however presented hereunder.


Hypothesis Testing 

In testing Hypotheses 1 and 2 of this study, the measures of nomination committee attributes as outlined in the Model above (Eqn. 5-7) were regressed against the measure of Earnings Management for the sampled companies in this study and the result is as presented in Table 3. 


As revealed by the results in Table 3, apart from Nomination Committee Diligence (NOMCDIL), the explanatory variables recorded negative coefficients with EARNMGT, though with relatively low values for their respective standard errors. The low values for the standard errors for all the variables are indications that the model is fit and the estimation of the relationship by the model is with a significant level of precision. Note that the negative coefficients recorded for most of the explanatory variables are indications that such variables NOMCIND, SALG and MKCP are negatively related with Earnings Management; whereas, NOMCDIL has a positive relationship with EARNMGT (coeff.= 0.0553504). The management of earnings by listed Nigerian non-finance firms will fall by 0.1995065 units for every unit increase in the nomination committee's level of independence. A 0.05 level of significance (p>|z| = 0.000) indicates that this result is extremely significant. The management of earnings by listed non-financial enterprises in Nigeria will similarly reduce by 0.0001772 and 0.0288782 units for every unit rise in SALG and MKCP, respectively.


Decision: With the above result p-value (0.0000) is significant at 0.05, the null hypothesis that Nomination/Governance Committee diligence and independence do not significantly influence Earnings Management of listed firms on Nigerian Exchange Group is rejected. This study therefore concludes that measures of nomination/governance committee diligence exert positive significant influence on earnings management of listed firms on Nigerian Exchange Group while nomination/governance committee independence exert negative significant influence on earnings management of listed firms on Nigerian Exchange Group.

CONCLUSION

On an individual note, while Remuneration Committee Independence (REMCIND) is found to have the capacity of exerting significant influence on earnings management, the same cannot be said of for Remuneration Committee Diligence (REMCDIL). The effectiveness of corporate governance attributes especially Nomination/Governance is to ensure better financial reporting, promoting transparency, accountability practices and protecting against corporate failure through established process of minimizing the effect of earnings management. This implies that the diligent and independent non-executive directors should be carefully nominated. This study thus recommends that:


Management of companies should not emphasis too much on the role of nomination/governance committee especially in the areas of diligence (frequency of meetings) but on the independence of nomination/governance committee in relation to earnings management.


Regulatory bodies should shift emphasis on how financial estimates prepared can be devoid of earnings management.

REFERENCES
  1. Lutfi, H. et al. "Strategi pemasaran food and beverage untuk meningkatkan penjualan pada masa pandemi Covid-19 di Cavinton Hotel Yogyakarta, Indonesia." Journal of Tourism and Economic, pp. 60–72, 2021.

  2. Hetty, K.T. "Program pendampingan strategi pemasaran digital." JSCD: Journal of Sustainable Community Development, vol. no. pp. 201–206, 2021.

  3. Adinda, R.H. "Analisis strategi pemasaran produk makcan food di masa pandemi Covid-19." Jurnal Mahasiswa Manajemen, vol. no. pp. 51–60, 2022.

  4. Anisa, L. et al. "Marketing mix strategy through SWOT analysis method at PT. Toyo Maitsu Surabaya." Enrichment: Journal of Management, vol. no. pp. 2721–7787, 2023.

  5. Chang, G.H. "Relationship between e-marketing mix strategy and integrated marketing communication: A conceptual framework." International Journal of Managerial Studies and Research (IJMSR), pp. 37–46, 2021.

  6. Andriyanto, L.S. "Analisis pengaruh bauran pemasaran (marketing mix 7-P) terhadap keputusan pembelian di Thiwul Ayu Mbok Sum." Jurnal Dinamika Sosial Ekonomi, pp. 26–38, 2020.

  7. Dess, G.G. "The role of entrepreneurial orientation in stimulating effective corporate entrepreneurship." Journal Academy of Management Executive, pp. 147–156, 2005.

  8. Sugiyono. Metode penelitian kombinasi (mix methods). Bandung: Alfabeta, 2015.

  9. Tjiptono, F. Strategi pemasaran. Yogyakarta: Andi, 2017.

  10. Nurul, H. et al. "Pengaruh segmentasi, targeting, positioning (STP) yang diintervening promosi pemasaran terhadap penjualan di UMKM Rocket Cafe." MABIS: Jurnal Manajemen Bisnis Syariah, pp. 1–6, 2023.

  11. Kotler, P.A. Marketing management. London: Pearson Education, 2016.

  12. Waehama, A. "Analisis strategi pemasaran dengan metode SWOT analysis dan marketing mix (studi kasus di UKM Susu Sapi Segar Wijaya)." Jurnal Agroindustri Pangan, pp. 32–45, 2022.

  13. Victor, V. et al. "SWOT analysis as a determinant of marketing strategy case." Almana: Jurnal Manajemen dan Bisnis, pp. 87–94, 2022.

  14. Yanmei, A. "On the impact of market segmentation and marketing mix strategy on enterprises." China Business and Commerce, pp. 22–23, 2014.

  15. Adhaghassani, F.S. Strategi bauran pemasaran (marketing mix) 7P (product, price, place, promotion, people, process, physical evidence) di Cherrykabakery. Yogyakarta: Universitas Negeri Yogyakarta, 2016.

  16. Rimes, J.M. "Analisis strategis e-business untuk strategi pemasaran dan penjualan." AITI: Jurnal Teknologi Informasi, pp. 111–124, 2023.

  17. Zhaohui, X. "On the application of SWOT marketing strategy in marketing." Economic Research Guide, pp. 55–56, 2017.

  18. Shivdasani, A. et al. "CEO involvement in the selection of new board members: An empirical analysis." The Journal of Finance, vol. 54, no. 5, pp. 1829–1853, 1999.

  19. Christensen, J. et al. "Corporate governance and company performance in Australia." Australian Accounting Review, vol. 20, no. 55, DOI:10.1111/j.1835-2561.2010.00108.x, 2010.

  20. Shen, S. et al. "Will the independent director institution work in China." Loyola of Los Angeles International and Comparative Law Review, vol. 27, no. 2, pp. 223–248, 2005.

  21. Osma, B. et al. "The effect of the board composition and its monitoring committees on earnings management: Evidence from Spain." Corporate Governance: An International Review, vol. 15, no. 6, pp. 1413–1428, 2007.

  22. Jensen, M.C. et al. "Theory of the firm: Managerial behaviour, agency costs and ownership structure." Journal of Financial Economics, vol. 3, no. 4, pp. 305–360, 1976.

  23. Eisenhardt, K. "Agency theory: An assessment and review." The Academy of Management Review, vol. 14, no. 1, pp. 57–74, 1989.

  24. Hill, C.W.L. et al. "Stakeholder-agency theory." Journal of Management Studies, vol. 29, no. 2, pp. 131–54, 1992.

  25. Pfeffer, J. "Size, composition and function of hospital boards of directors: A study of organization-environmental linkage." Administrative Science Quarterly, vol. 18, no. 3, pp. 349–364, 1973.

  26. Haniffa, R.M. et al. "Culture, corporate governance and disclosure in Malaysian corporations." Abacus, vol. 38, no. 3, pp. 317–349, 2002.

  27. Nicholson, G.J. et al. "Board composition and corporate performance: How the Austrian experience informs contrasting theories of corporate governance." Corporate Governance: An International Review, vol. 11, no. 3, pp. 189–205, 2003.

  28. Agyemang-Mintah, P. "The nomination committee and firm performance: An empirical investigation of UK financial institutions during the pre/post financial crisis." Corporate Board: Role, Duties & Composition, vol. 11, no. 3, pp. 176–190, 2015.

  29. Monye-Emina, H.E. et al. "Determinants of the credibility of audit reports in the Nigerian insurance sector." Illorin Journal of Management Sciences, vol. 5, no. 1, pp. 1–12, 2014.

  30. Jeroh, E. et al. "Impact assessment of bank consolidation on the performance of commercial banks in Nigeria." Acta Universitatis Danubius Oeconomica, vol. 11, no. 5, pp. 30–44, 2015.

  31. Jeroh, E. et al. "Interest rate regime and the performance of the Nigerian capital market." Studies and Scientific Researches, Economics Edition, vol. 22, pp. 43–54, 2015.

  32. Jeroh, E. "Does book values and earnings affect equity values of corporate entities in Nigeria." Trends Economics and Management, vol. 10, no. 27, pp. 30–38, 2016.

  33. Jeroh, E. "The effect of board and ownership structure on the financial performance of listed firms." Nigerian Journal of Management Sciences, vol. 6, no. 2, 196–205, 2018.

  34. Jeroh, E. "An assessment of the internal determinants of the environmental disclosure practices of firms across Sub-Saharan Africa." Ekonomski Horizonti, vol. 22, no. 1, pp. 47–59, 2020.

  35. Jeroh, E. "Assessing the nexus between forensic accounting, the Finance Act, 2019 and tax revenue in Nigeria." Journal of Forensic Accounting and Fraud Investigation, vol. 4, no. 2, pp. 213–238, 2019.

License
CC BY-NC-ND
Creative Commons Attribution-NonCommercial-NoDerivatives 4.0 International License
Impact of Nomination and Governance Committee Attributes on Earnings Management of Listed Firms on the Nigerian Exchange Group © 2026 by Peter-Mario Efesiri EFENYUMI, John Ugochukwu NWOYE, Emmanuel Ikechukwu OKOYE licensed under CC BY-NC-ND 4.0
All papers should be submitted electronically. All submitted manuscripts must be original work that is not under submission at another journal or under consideration for publication in another form, such as a monograph or chapter of a book. Authors of submitted papers are obligated not to submit their paper for publication elsewhere until an editorial decision is rendered on their submission. Further, authors of accepted papers are prohibited from publishing the results in other publications that appear before the paper is published in the Journal unless they receive approval for doing so from the Editor-In-Chief.
Himalayan Journal of Economics and Business Management open access articles are licensed under a Creative Commons Attribution-Share A like 4.0 International License. This license lets the audience to give appropriate credit, provide a link to the license, and indicate if changes were made and if they remix, transform, or build upon the material, they must distribute contributions under the same license as the original.
Recommended Articles
Research Article
Resonant leadership and its role in achieving organizational success: An Exploratory study of the opinions of a sample of employees of the Baghdad Municipality-Baghdad Water Department-Southern Reservoir
Download PDF
Research Article
Modelling Structure Job Quality, Job Design and Job Satisfaction
...
Published: 30/08/2022
Download PDF
Research Article
Influence of Leadership on Poverty Reduction in the Devolved Government in Trans-Nzoia County, Kenya
...
Published: 30/06/2021
Download PDF
Research Article
Analysis Of the Influence of Leadership Style and Organizational Culture on Teacher Performance State Vocational School 4 Pontianak City
...
Published: 07/08/2024
Download PDF
Flowbite Logo
Najmal Complex,
Opposite Farwaniya,
Kuwait.
Email: support@himjournals.com

Useful Links
Order Hard Copy
Privacy policy
Terms and Conditions
Refund Policy
Others
About Us
Team Members
Contact Us
Online Payments
Join as Editor
Join as Reviewer
Subscribe to our Newsletter
Follow us
MOST SEARCHED KEYWORDS
scientific journal
 | 
business journal
 | 
medical journals
 | 
Scientific Journals
 | 
Academic Publisher
 | 
Peer-reviewed Journals
 | 
Open Access Journals
 | 
Impact Factor
 | 
Indexing Services
 | 
Journal Citation Reports
 | 
Publication Process
 | 
Impact factor of journals
 | 
Finding reputable journals for publication
 | 
Submitting a manuscript for publication
 | 
Copyright and licensing of published papers
 | 
Writing an abstract for a research paper
 | 
Manuscript formatting guidelines
 | 
Promoting published research
 | 
Publication in high-impact journals
Copyright © Himalayan Journals . All Rights Reserved.